1Our No. 1
Casino
Crusado
Welcome bonus150% up to £3,500+ 125 FS
Min. deposit£20
Payout1 h
Games7,500+
Score9.6of 10
18+. New customers only. Operator T&Cs apply.
18+Adults only. Please gamble responsibly.
With 0 banking credentials stored by the operator, the safest bank transfer casinos process British player deposits directly through regulated Open Banking networks. You authorise each transaction inside your personal banking app rather than typing card numbers into a cashier screen. Every transfer relies on encrypted tokens and strict identity checks to protect your account balance.
 By Joanna Thompson
Crusado
18+. New customers only. Operator T&Cs apply.
Peaches
18+. New customers only. Operator T&Cs apply.
Let's Jackpot
18+. New customers only. Operator T&Cs apply.
Winzter
18+. New customers only. Operator T&Cs apply.
Uspin
18+. New customers only. Operator T&Cs apply.
Instaspin
18+. New customers only. Operator T&Cs apply.
Betninja
18+. New customers only. Operator T&Cs apply.
Betzino
18+. New customers only. Operator T&Cs apply.
Sending money via bank transfer is safe because Open Banking redirects you to your own bank's environment, keeping 0 login credentials on casino servers.
| Security Layer | Safe Open Banking Transfer | Manual UK Bank Wire | Debit Card Payment |
|---|---|---|---|
| Credential storage at casino | None; redirected to bank portal | Sort code and account number shared | Long card number and CVV stored |
| SCA and biometric approval | Mandatory on every single deposit | Required when setting up new payee | Triggered periodically by card issuer |
| Account number compromise risk | Tokenised reference hides sensitive data | Visible on manual payment instruction | Exposed if merchant database is breached |
| Closed-loop withdrawal protection | Locked to originating bank account | Verified against sort code ownership | Returned to the original debit card |
When players ask if is sending money via bank transfer safe compared to cards, the main difference is credential exposure. Under the Gambling Commission credit card prohibition, British operators cannot accept credit cards, leaving debit cards and direct bank transfers as the primary funding options. The comparison below shows that direct banking removes static card number storage across 4 critical security layers.
Players who prefer authorising payments on their handset can review dedicated app bank transfer casinos for mobile-specific banking steps.
Strong Customer Authentication requires 2 independent verification factors before any UK bank releases funds to a gambling merchant.
Your banking app combines device possession with Face ID, a fingerprint scan, or a passkey. Even if a third party accesses your casino account, they cannot initiate a deposit without physical biometric approval on your registered phone.
An Open Banking deposit generates 1 single-use cryptographic token that expires immediately after the exact payment amount is settled.
Unlike recurring card mandates, Pay by Bank APIs do not grant the operator ongoing authority to pull funds from your current account. Every subsequent top-up requires a fresh login and biometric confirmation for that specific sum. Unlicensed sites often lack secure payment systems and raise serious data protection concerns, so checking how your payment token is handled is essential before depositing.
To see how quickly these tokenised payments clear in practice, compare the processing times at an instant bank transfer casino uk.
Every legitimate Open Banking gateway operating in Great Britain must hold authorisation as a Payment Initiation Service Provider and work alongside operators licensed by the Gambling Commission.
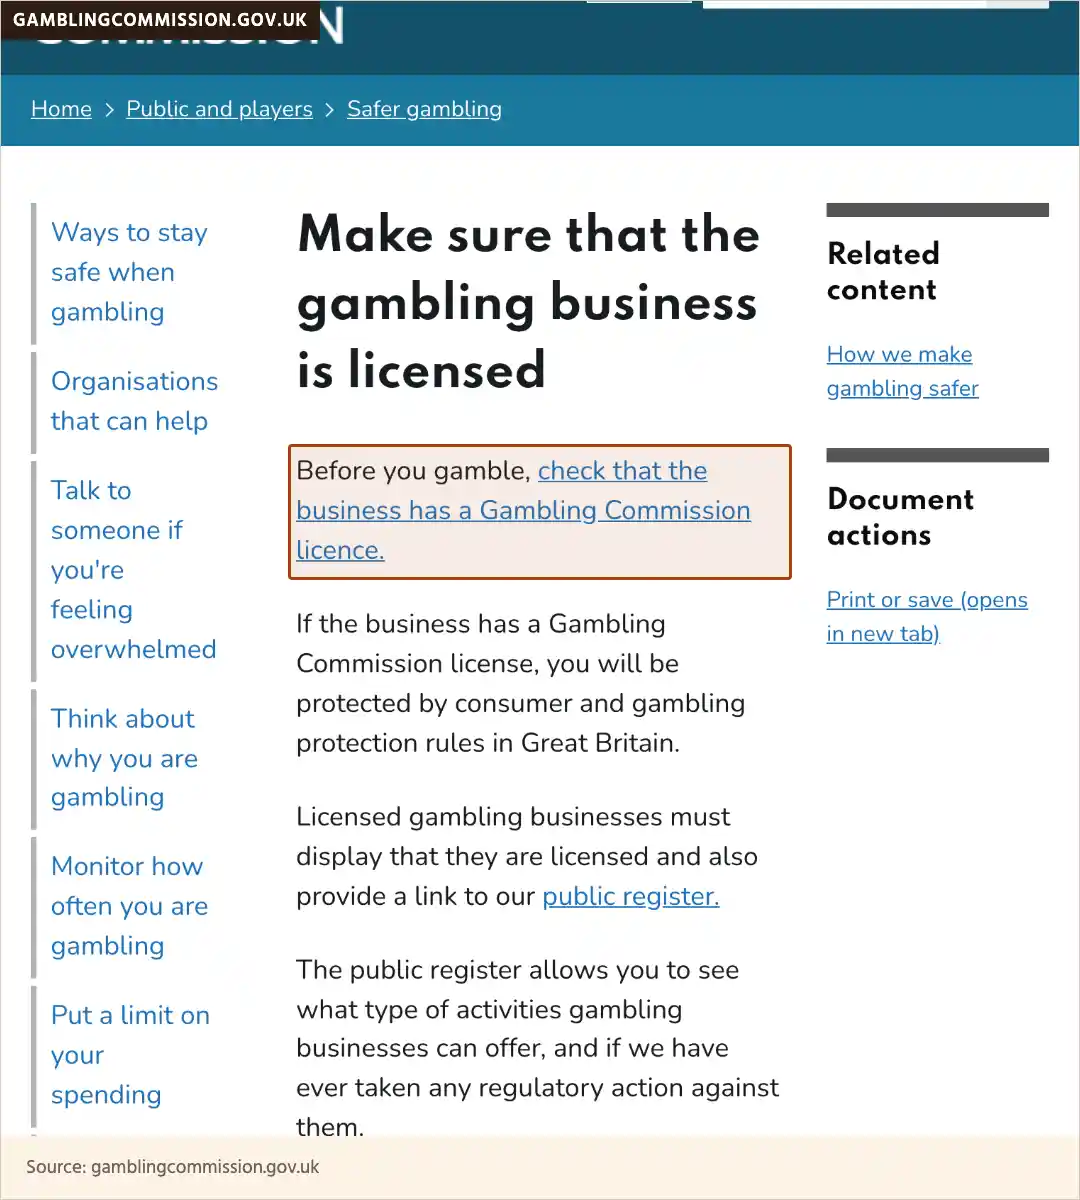
Before you deposit, the Gambling Commission advises checking that the gambling business holds a valid operating licence, as licensed businesses must display their status clearly on the site. Under the Gambling Act 2005, providing gambling facilities to British consumers without this licence is illegal, and a permit issued in another country does not authorise operations in Great Britain.
Players can verify any third-party payment gateway rapidly by matching the company name on the payment screen against the official register.
When the redirect window opens, look for the regulated entity name and registration number in the footer before selecting your bank. If a site hides the payment processor identity or operates without British consumer protection rules, cancel the transfer immediately.
Operated under Pay.UK oversight, the Faster Payment System supports individual transfers of up to 1 million pounds while CHAPS handles high-value settlements.
When players ask what is the safest money transfer for substantial casino deposits or jackpot withdrawals, direct bank rails offer bank-grade encryption and real-time settlement. Running since 2008, the Faster Payment System operates 365 days per year, though individual UK banks set their own daily transaction limits for customer accounts. In addition, customer gambling winnings in Great Britain are 0 tax-free regardless of the payout size, meaning large bank withdrawals arrive without tax deductions.
You can evaluate which licensed operators support high-limit direct banking in our guide to the best bank transfer casinos.
A Payment Initiation Service Provider receives 0 access to your transaction history or spending habits during a standard deposit.
Open Banking separates payment initiation from account information services under strict technical permissions. When you approve a casino transfer, the bank only confirms whether your available balance covers the requested deposit and returns a success or failure code to the merchant. Your salary credits, direct debits, and everyday retail purchases remain completely hidden unless you separately consent to an affordability check.
Compliance teams at safe bank transfer casinos accept redacted PDF or paper statements where unrelated personal purchases are blacked out, provided 4 core account identifiers remain clear.
Because unlicensed sites pose serious risks of identity theft and fraud, you should only upload verification documents to operators covered by British consumer protection rules. Redacting non-gambling lines protects your financial privacy while still allowing the operator's verification department to confirm account ownership.
Matching your sort code and full name against the deposit record proves that the funding bank account belongs to you.
Verification officers must confirm that no third party is funding the gambling account. Once the sort code, account number, and holder name are matched, the security hold lifts without requiring visibility into your personal household budget.
Closed-loop anti-fraud policies require operators to return the entirety of withdrawn funds up to your original deposit back to the exact bank account used to fund the balance.
If an unauthorised person gains access to your casino profile, they cannot divert your balance to an external e-wallet or an unverified sort code. The cashier system automatically locks the payout route to the verified bank account established during your initial Open Banking or wire deposit.
Once your bank details pass this ownership check, subsequent payouts move rapidly at a fast bank transfer casino.
Every operator regulated by the Gambling Commission must classify player funds into 1 of 3 insolvency protection tiers within its terms and conditions.
Unlike a standard UK bank current account, money held in a gambling wallet is not covered by the Financial Services Compensation Scheme. Instead, licensed operators must disclose whether customer balances hold Basic, Medium, or High protection in the event of company insolvency. Keeping only your active playing budget in the casino wallet and withdrawing surplus winnings back to your bank account minimises exposure.
If a payment dispute with a licensed casino remains deadlocked after 8 weeks, you can escalate the case to an Alternative Dispute Resolution (ADR) provider for free.
The Gambling Commission states that you must first complete the operator's internal complaints procedure before approaching an ADR body, and notes that ADR providers do not handle general customer service complaints. By contrast, unlicensed sites lack appropriate dispute resolution schemes and can block payouts with no independent recourse. All Gambling Commission licensees are also required to participate in GAMSTOP since 31 March 2020, which offers a shortest self-exclusion period of 6 months up to 5 years and requires at least a 24-hour cooling-off period when contacting them to deactivate.
Players researching how regulatory oversight differs outside the British framework can read our overview of non gamstop bank transfer casinos.
Direct bank transfers are safer because 0 static payment numbers are stored on the casino's servers. You authorise a single-use token inside your banking app using biometrics rather than sharing a long card number and CVV.
Licensed UK operators must state their exact fund protection tier—Basic, Medium, or High—in their terms and conditions and at the point of deposit. Always check this disclosure before transferring money so you know whether balances sit in an independent trust account.
Yes, provided your own full name appears on the joint bank statement alongside the sort code and account number. Some operators require both account holders to complete identity verification before releasing withdrawals back to a shared account.
A Faster Payments ID is a unique reference number assigned to every real-time transfer routed through Pay.UK rails. If a withdrawal takes longer than expected, you can request this reference from the casino cashier so your bank can locate the settlement.
Gambling Commission rules require players to go through the operator's internal complaints procedure first. You can refer the dispute to a free, independent ADR provider once 8 weeks have elapsed or if the casino issues a final deadlock letter earlier.
This site is for adults. Set a limit on your deposits and on your time before you play. If gambling is causing you harm, put your name on your national self-exclusion register and find help at www.gamcare.org.uk.